

Data centre boom deepens strain on Australia builders
Wed, 16th Sep 2026 (Today)
Australia's data centre development pipeline is intensifying pressure on the construction sector, according to CreditorWatch, with the strain most acute in residential building.
The latest Business Risk Index values the national data centre pipeline at more than AUD $150 billion through 2030. New South Wales and Victoria account for about 91% of projects tracked by CommBank, concentrating demand for land, labour and specialist trades in two of the country's busiest building markets.
CreditorWatch's analysis points to a split industry. Commercial builders and engineering contractors tied to data centre projects face a large pool of specialist work, while residential construction is grappling with arrears, payment defaults and insolvencies after a housing downturn.
Construction recorded a 60-plus-day payment arrears rate of 6.5% over the past 12 months, the fourth highest among the 18 industries monitored by CreditorWatch. Arrears in the sector rose 13.3% over the year.
The pressure is not spread evenly. Much of the financial strain sits in residential building rather than in the commercial construction work likely to benefit from data centre investment.
Trade payment default rates and tax defaults also point to stress in the housing segment. Construction posted the third-highest trade payment default rate of any industry at 1.94%, while its ATO tax default rate of 1.58% was the second highest.
In August, first-time insolvencies in construction rose to 868, sharply above the roughly 300 a month recorded through much of the previous year. Total first-time insolvencies across the economy climbed to 1,834, with construction accounting for a large share of the increase.
According to the report, that jump was concentrated in residential building, adding to evidence that the housing segment remains under heavier pressure than parts of construction exposed to commercial and infrastructure contracts.
Capacity strain
CreditorWatch argued that the main economic effect of the data centre build-out may be greater competition for scarce resources rather than broader relief for the construction sector. Data centre projects require electrical, mechanical, cooling, communications, controls, fire protection and commissioning work, driving demand for specialist subcontractors, equipment suppliers and builders.
That demand could deepen shortages of skilled labour and materials already affecting housing and essential infrastructure. Smaller residential builders are especially exposed because they have less room to absorb higher wages, longer procurement times and tighter working capital conditions.
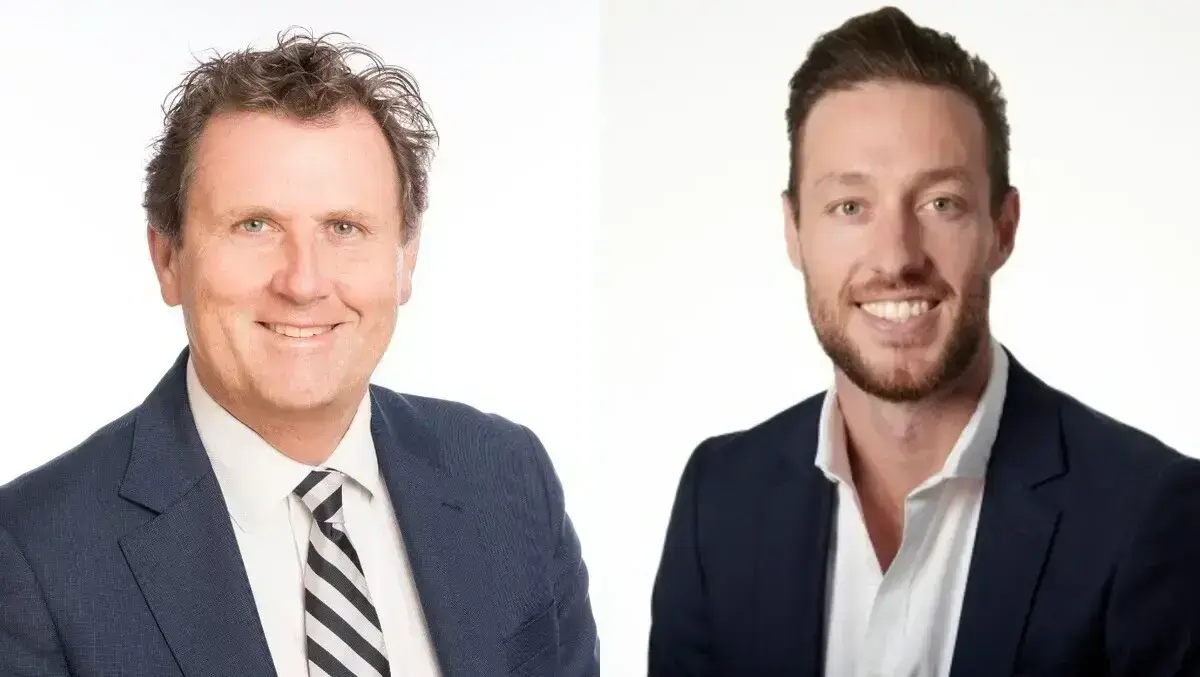
Patrick Coghlan, Chief Executive Officer of CreditorWatch, said the project pipeline was landing in an industry already showing divergent credit conditions.
"A $150 billion pipeline is being poured into a construction sector that's already seeing credit pressures running at two speeds. The commercial firms geared to data centre work are looking at years of high-value activity, but the residential end is still absorbing rising defaults, tight cash flow and higher input costs.
"The risk is that this boom draws skilled labour and materials away from housing and essential infrastructure at exactly the time we can least afford it. Australia doesn't have a shortage of demand for construction - it has a shortage of capacity to deliver it. That's the real test the numbers are pointing to.
"Approvals tell you where the money wants to go. They don't tell you whether an industry has the workforce, the supply chains and the balance-sheet strength to build it. That gap is where the pressure will show up first," Coghlan said.
Default warning
Trade payment defaults remain one of the clearest early signs of business distress, CreditorWatch said. Its data shows a business with four or more registered trade payment defaults has an insolvency rate of about 19%, compared with well under 1% for a business with none.
That measure matters because contractors can appear to be growing while their cash position weakens. Long delivery schedules, labour shortages, procurement delays and cost escalation can leave a business exposed even when revenue is rising.
For residential builders, the problem is more direct. They can face the same industry-wide rise in wages and materials costs without access to the specialist work and margins available in commercial data centre projects.
Broader outlook
CreditorWatch said the pressures on construction reflect a more complicated national business backdrop. It cited geopolitical tensions, higher fuel costs, rising labour costs and the global rush to invest in artificial intelligence infrastructure as factors adding to inflation and tightening credit conditions.
Oil prices rising back to around USD $100 a barrel, alongside the end of Australia's fuel excise subsidies, have lifted transport and input costs for businesses. That squeeze is hitting both companies and consumers, reducing discretionary spending while raising operating expenses.
At the same time, the investment surge linked to artificial intelligence is lifting demand for non-residential construction and raw materials. CreditorWatch said central banks are increasingly paying attention to the near-term inflation effects of that build-out as well as its longer-run implications.
Ivan Colhoun, Chief Economist at CreditorWatch, said businesses were already dealing with years of rising costs and relatively high borrowing costs.
"Businesses have already been experiencing elevated rates of cost increase for many years and the equal highest interest rates in over a decade," Colhoun said.
"Recent increases in fuel costs, the unwise quantum of this year's Minimum Wage increase and a prospective further interest rate rise in September will add to these pressures.
"The winning sectors are likely to be parts of Mining, parts of Construction and other businesses that might directly benefit from the AI investment boom - businesses providing services to these sectors including Finance and Professional Services.
"At the same time, any companies with high debt loads, sectors where fuel is a significant input or transport costs are significant, as well as sectors exposed to consumers' discretionary spending, are also likely to face more challenging operating conditions," Colhoun said.