

Australian businesses upbeat despite cash flow strain
Wed, 23rd Sep 2026 (Today)
CreditorWatch has found that Australian businesses remain optimistic about their own growth prospects, even as views on broader trading conditions have weakened.
The research covered 1,015 business decision-makers across sole traders, micro businesses, small businesses and medium-sized enterprises.
Seven in 10 respondents said they were somewhat or very optimistic about their business's growth prospects over the next 12 months. At the same time, 29 per cent rated the current climate for Australian businesses as poor or very poor, up from 19 per cent in the previous survey period.
Positive views of current conditions also declined. The share rating conditions as good or very good fell to 38 per cent from 49 per cent, highlighting a widening gap between sentiment about individual businesses and the broader economy.
Optimistic respondents most often pointed to customer demand, project pipelines, expansion plans, technology including artificial intelligence, and strong business fundamentals. Negative responses were more likely to cite cost-of-living pressure on demand, government policy, a weak economy, rising operating costs and lower customer spending.
Cash pressure
The findings also highlighted pressure on working capital. CreditorWatch found that 41 per cent of business decision-makers had used personal funds to support business working capital during the previous 12 months, with 12 per cent doing so regularly and 29 per cent occasionally.
One in three respondents said they currently rely on personal funds to support working capital, suggesting many owners are using their own money to bridge gaps as trading conditions become more difficult.
Cash reserves were limited for many firms in the survey. If revenue stopped immediately, 49 per cent said their available cash and liquid reserves would cover operating expenses for no more than six months.
Within that group, 23 per cent said they could last no more than three months. Eight per cent reported having less than one month of reserves available.
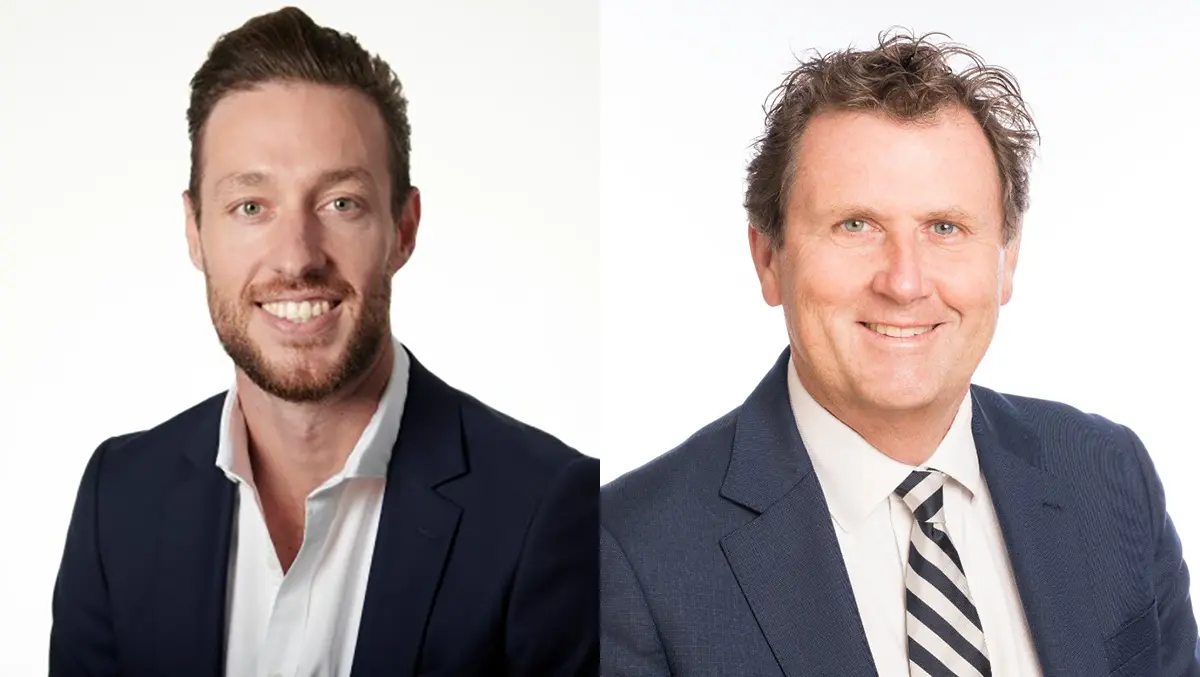
Ivan Colhoun, Chief Economist, CreditorWatch, said the mix of optimism and strain points to a growing mismatch between confidence and resilience.
"These findings show that business confidence and financial resilience are not necessarily moving together. The survey shows that businesses are more negative about the operating environment than they were a year ago, yet seven in 10 remain optimistic about their own growth prospects. That may reflect confidence in their own ability to adapt, win customers, and use technology to improve productivity, rather than a belief that the broader economy is becoming easier to navigate. Cost-of-living pressures, high operating costs, and softer customer spending are still prominent concerns. When those pressures sit alongside limited cash reserves, even businesses with sound long-term prospects can become vulnerable to revenue interruption or slower customer payments," said Colhoun.
Thin buffer
The survey points to a fragile position for some smaller operators, as pressure on business cash flow can quickly spill into household finances. That is especially true where owners are funding day-to-day operations from personal resources.
Patrick Coghlan, Chief Executive Officer, CreditorWatch, said: "There is real resilience in these results, but resilience should not be confused with unlimited capacity to absorb shocks. When 41 per cent of business decision-makers have used personal funds to support working capital in the past year, it suggests that the financial boundary between the business and the owner can become very thin. That may keep an otherwise viable business moving through a difficult period, but it can also mask how tight underlying cash flow has become.
"The human impact matters as well. In the survey's open-ended responses, some business owners explicitly referred to the mental weight of entrepreneurship and the effect business and personal pressures can have on mental health. Those comments are a reminder that financial pressure does not stop at the company balance sheet.
"For businesses extending trade credit, the practical lesson is to avoid relying on reputation, history, or a one-off credit check. Customer circumstances can change quickly. Ongoing monitoring of payment behaviour and other risk signals can help businesses identify deterioration earlier and review credit limits, terms, or collections activity before exposure grows.
"For business owners themselves, the same principle applies: they should know their cash position, understand where customer concentration and late payments could hurt them, and act early when warning signs emerge."
The data offers a snapshot across several layers of the Australian business base, from sole traders to companies with up to 499 employees. That breadth matters because the survey captures firms that are often more exposed to swings in consumer demand, payment delays and borrowing costs than larger listed groups.
While the overall findings show a notable degree of confidence at the firm level, the detail suggests that confidence may depend on owners continuing to absorb risk personally. Nearly half of those surveyed said they would have six months or less of cash cover if revenue dried up, underlining how little room many businesses have for disruption.
For lenders, suppliers and other companies offering trade credit, the picture is mixed: businesses may still expect growth, but a sizeable share are operating with limited liquidity and increasingly blurred financial boundaries between company and owner. One in three respondents said they currently rely on personal funds to support working capital.